Using a vehicle for work does not make the entire car deductible. Federal tax law generally allows a deduction only for qualifying business use, and the result depends on how you calculate vehicle costs, how much you drive for business, and whether you bought, leased, or financed the vehicle.
For 2026, business drivers can generally choose between the IRS standard-mileage method and the actual-expense method. A separate temporary deduction may also apply to interest on certain personal vehicle loans, but it does not cover leases or used vehicles.

As an Amazon Associate I earn from qualifying purchases.
What a vehicle tax write-off actually means
A write-off is a tax deduction, not a dollar-for-dollar refund. If you claim a $5,000 vehicle deduction and are in a 22% marginal federal tax bracket, the deduction may reduce federal income tax by roughly $1,100—not by $5,000.
Only the qualifying portion of vehicle use is generally deductible. Personal driving and ordinary commuting are not business expenses. State tax rules may differ from federal rules, so the information here focuses on federal income tax.
#1 Best Overall

- KEEP PERFECT RECORDS: Adams Vehicle Mileage and Expense Journals help you log business use of your car or truck with year start and year end odometer readings and flawless daily records
- GET THE BEST DEDUCTION: 588 entries capture the date, odometer readings, total miles and business purpose—everything you need to document business use for the IRS
- SUMMARIES MAKE TAX TIME EASY: Annual summary pages hold monthly mile totals to calculate percentage of business use; monthly maintenance totals help you deduct unreimbursed vehicle expenses
- INCLUDES 6 RECEIPT POCKETS: Don’t forget to save receipts; you get 2 double-sided pockets for oil changes and other service; 2 pockets for repairs, and 2 pockets for parking and tolls
- KEEP IT IN THE CAR: This portable 5-1/4 x 8-1/4 booklet was meant to travel with you; keep one in each glove compartment for a complete record of business use
Who can claim a vehicle deduction?
- Self-employed people and sole proprietors: Usually report qualifying vehicle expenses on Schedule C, line 9.
- Partnerships, S corporations, and corporations: Generally report vehicle costs on the applicable business return.
- Employees: Most cannot deduct unreimbursed vehicle expenses on their federal return. Employer reimbursement through an accountable plan is usually the practical route.
Narrow exceptions can apply to certain Armed Forces reservists, qualified performing artists, and fee-basis state or local government officials.
The two ways to deduct business vehicle use
Business owners generally compare these two methods:
- The standard-mileage method
- The actual-expense method
Calculate both when you are eligible. The larger deduction is not automatically available, however, because each method has restrictions.
Recommended Free Tools
2026 IRS standard-mileage rates
| Type of driving | January 1–June 30, 2026 | July 1–December 31, 2026 |
|---|---|---|
| Business | 72.5 cents per mile | 76 cents per mile |
| Medical | 20.5 cents per mile | 23.5 cents per mile |
| Charitable | 14 cents per mile | 14 cents per mile |
| Qualifying military moving | 20.5 cents per mile | 23.5 cents per mile |
The 2025 business rate was 70 cents per mile. Because the 2026 business rate changes partway through the year, separate the miles driven in each period.
How the standard-mileage method works
The basic calculation is:
Qualifying business miles × applicable IRS rate = mileage deduction
For example, 8,000 business miles driven between July and December 2026 would produce a standard-mileage deduction of $6,080 before adding eligible parking and tolls.
Business parking fees and tolls can generally be added separately. The mileage rate already accounts for gasoline, oil, repairs, maintenance, tires, insurance, registration, lease payments, and depreciation. Do not deduct those same costs again for the same vehicle and year.
When standard mileage is unavailable
You generally cannot use the standard-mileage method if you:
Rank #2
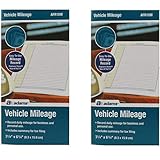
- Sold As 2 Journals
- Adams Vehicle Mileage 3 1/4 x 6 1/4
- Record daily mileage for business and personal use
- Includes summary for tax filing
- Use five or more vehicles simultaneously in the business, such as in a fleet.
- Claim MACRS depreciation for the vehicle.
- Claim Section 179 or bonus depreciation for it.
- Use a depreciation method other than straight-line depreciation.
- Claim actual vehicle expenses after 1997 for a leased vehicle.
For an owned vehicle, choosing standard mileage in the first year it is available for business use generally preserves the option to continue using it later. For a leased vehicle, choosing standard mileage generally commits you to that method for the entire lease term.
How the actual-expense method works
With actual expenses, you total eligible vehicle costs and multiply them by the business-use percentage:
Allowable vehicle costs × business-use percentage = business deduction
Potentially deductible costs include:
- Gasoline and oil
- Repairs and maintenance
- Tires
- Insurance
- Registration and license fees
- Lease payments
- Depreciation
- Business parking and tolls
- The business portion of vehicle-loan interest
If the vehicle was driven 60% for business and total allowable costs were $12,000, the business portion would generally be $7,200. The remaining $4,800 is personal and not deductible as a business expense.
How to calculate business-use percentage
Keep separate totals for:
- Business miles
- Commuting miles
- Other personal miles
- Total miles for the year
A simple percentage calculation is:
Business miles ÷ total miles = business-use percentage
Commuting miles do not belong in the business total. Depreciation and actual operating costs must generally be reduced for personal use.
Commuting is not business mileage
Driving from home to your regular workplace is generally personal commuting, even if you make a phone call, carry tools, or keep work materials in the vehicle. A personal errand does not become business mileage merely because it is combined with a work trip.
Free tools Windows power users keep installed
One-click scans. No signup required.
Driving between workplaces, to customers, suppliers, or qualifying temporary work locations may be business transportation when there is a genuine business purpose and adequate documentation.
Rank #3

- Comprehensive Package for Long Term Use: this package comes with 6 auto mileage and expense notebooks; Each mileage log book for car contains 32 pages; This sufficient quantity enables you to keep track of your expenses for a longer period
- Ideally Sized for Convenience: with dimensions of 6.3 x 3.3 inches, the vehicle mileage log book is the ideal size to carry around; Its compact nature ensures you can easily tuck it into your glove compartment or bag, ready to jot down important information whenever the need arises
- Quality Material for Ease of Use: the vehicle book is made from quality paper, providing a smooth writing surface for all your record keeping needs; This ensures clear documentation of all your auto mileage and expenses for easy reference
- Organized Layout for Detailed Record Keeping: each car mileage log book boasts an organized layout with appropriate categories; You can track different types of expenses like mileage, oil changes, parking charges, and even cleaning and repair costs; The 2 page layout allows you to track expenses by day over a 12 months period, with monthly and annual summary pages on the back for easy accurate recording; This gives you a clear and broad view of your vehicle's running costs
- Ideal for Divers: the mileage tracking book constitutes the ideal tool for divers with features specifically designed for auto mileage and expense logging; They provide a systematic way of recording mileage, gas usage, oil changes, and other vehicle related expenses incurred
Buying a vehicle: depreciation, Section 179, and bonus depreciation
Buying a vehicle does not normally allow you to deduct the entire purchase price immediately. The cost is generally recovered through depreciation, subject to business-use requirements, vehicle classification, passenger-vehicle limits, and other statutory restrictions.
Section 179 limits
For tax years beginning in 2026:
- Maximum Section 179 deduction: $2,560,000
- Phaseout begins when total Section 179 property placed in service exceeds $4,090,000
- Section 179 limit for qualifying sport utility vehicles: $32,000
For comparison, the 2025 amounts were $2,500,000, a $4,000,000 phaseout threshold, and a $31,300 SUV limit.
Section 179 has additional requirements, including taxable-income and business-use rules. A vehicle generally must be used more than 50% for qualified business purposes to receive the same accelerated treatment available to a vehicle with lower business use. The deduction is also limited by the business’s taxable income.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallCrashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteBonus depreciation
Under the One, Big, Beautiful Bill, 100% additional first-year depreciation is generally available for eligible depreciable property acquired after January 19, 2025, if the property meets the applicable requirements. Certain used vehicles may qualify; used property is not automatically excluded.
Bonus depreciation is separate from the standard-mileage method. Claiming bonus depreciation generally prevents you from using standard mileage for that vehicle. Automobile depreciation limits and the business-use percentage can still restrict the deduction.
Passenger-vehicle limits
For passenger automobiles placed in service during 2025, the IRS lists maximum first-year depreciation amounts of:
- $20,200 when the Section 168(k) additional first-year depreciation deduction applies
- $12,200 when it does not apply
The listed later-year limits are $19,600 for the second year, $11,800 for the third year, and $7,060 for each succeeding year. These limits are reduced for personal use. The limits—not the vehicle’s full purchase price—may control the deduction for an ordinary passenger car.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Does a heavy SUV qualify for a full write-off?
No. A heavy SUV is not automatically fully deductible. Its treatment can depend on its gross vehicle weight rating, whether it qualifies for Section 179, the Section 179 SUV limit, bonus-depreciation rules, business-use percentage, taxable income, passenger-vehicle rules, and possible depreciation recapture.
Rank #4

- Sold as 1 EA.
- Mandatory records for all who use their automobile for business purposes. Records mileage, parking fees and tolls.
- Features a detachable year-end summary for tax advisor.
- Undated-start any time.
- Good for one full year.
Check the vehicle’s certification label and tax classification rather than relying on its marketing description. A pickup, van, or SUV can have different treatment depending on its design and weight rating.
Leasing a vehicle for business
A business-leased vehicle can generally be handled under either standard mileage or actual expenses, subject to the method restrictions.
Under actual expenses:
- Only the business portion of lease payments is deductible.
- Advance payments must generally be spread over the lease term.
- Amounts that function economically as purchase payments are not treated as ordinary lease payments.
- A lease lasting 30 days or more may require an IRS lease-inclusion amount, which reduces the deductible lease expense.
Personal and commuting use remains nondeductible. Lease payments also do not qualify for the temporary personal vehicle-loan-interest deduction described below.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Scan for outdated or missing drivers - takes under a minute3Repair Windows errors before they cause bigger problemsVehicle-loan interest
Business-use loan interest
Under the actual-expense method, the business portion of interest on a vehicle loan may generally be deductible when the vehicle is used in a trade or business. Allocate the interest between business and personal use.
Do not deduct the same interest twice. For example, interest claimed as a business expense on Schedule C cannot also be claimed as a personal deduction on Schedule 1-A.
Temporary personal car-loan-interest deduction
For tax years 2025 through 2028, individuals may deduct up to $10,000 per year of qualified interest on certain personal passenger-vehicle loans. This is an above-the-line deduction, so it can be available whether or not you itemize.
Generally, the vehicle and loan must meet all of these conditions:
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
- The loan was originated after December 31, 2024.
- The loan was used to purchase the vehicle.
- The vehicle is for personal use, not business or commercial use.
- The loan is secured by a first lien on the vehicle.
- The vehicle is new to the taxpayer; used vehicles generally do not qualify.
- The vehicle is a qualifying car, minivan, van, SUV, pickup truck, or motorcycle.
- The vehicle has a gross vehicle weight rating below 14,000 pounds.
- Final assembly occurred in the United States.
The deduction phases out as modified adjusted gross income exceeds $100,000, or $200,000 for married taxpayers filing jointly. Lease payments do not qualify.
Where to claim the personal interest deduction
For a 2025 federal return filed in 2026:
- Complete Schedule 1-A (Form 1040), Part IV — No Tax on Car Loan Interest.
- Attach Schedule 1-A to Form 1040, Form 1040-SR, or Form 1040-NR.
- Follow the Form 1040 instructions to carry the deduction to the return.
Schedule 1-A, Part IV asks for the vehicle identification number and separates interest already deducted on Schedule C, Schedule E, or Schedule F from interest claimed on Schedule 1-A.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.How to report vehicle expenses
| Situation | Common federal reporting location |
|---|---|
| Sole proprietor’s operating expenses or standard mileage | Schedule C, line 9 |
| Sole proprietor’s depreciation | Schedule C, line 13; Form 4562 when required |
| Sole proprietor’s lease payments | Schedule C, line 20a |
| Vehicle-use information | Schedule C, Part IV or Form 4562, Part V, depending on the situation |
| Personal qualified car-loan interest | Schedule 1-A, Part IV, for 2025 returns |
Schedule C, Part IV is generally used when claiming standard mileage, leasing a vehicle, or using a fully depreciated vehicle when Form 4562 is not otherwise required. Form 4562, Part V is used when claiming depreciation or when Form 4562 is otherwise required.
Vehicle records the IRS expects
A mileage app, spreadsheet, diary, or written log can work if it reliably records the necessary information. Records should be created at or near the time of each trip—not reconstructed from memory in December.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →For each business trip, record:
- Date
- Destination or area
- Business purpose
- Beginning and ending odometer readings, or miles driven
- Business miles
- Total annual mileage
- Parking and toll amounts
- Receipts for actual vehicle expenses
The IRS generally does not accept amounts that are merely estimated or approximated. Keep records supporting a deduction for at least three years from the date the return is filed. Retain depreciation and basis records throughout the vehicle’s recovery period and longer when a later sale or disposition could create a tax issue.
Common vehicle write-off mistakes
- Claiming the entire vehicle: Only qualifying business use is deductible, and depreciation limits may apply.
- Claiming mileage plus gasoline: The standard-mileage rate already includes ordinary operating costs.
- Counting commuting: Home-to-regular-workplace travel is generally personal.
- Using standard mileage after bonus depreciation: Claiming bonus depreciation generally prevents standard mileage for that vehicle.
- Assuming employees can use Schedule A: Most employees cannot deduct unreimbursed vehicle expenses federally.
- Double-counting loan interest: Interest cannot be deducted both as a business expense and as personal car-loan interest.
- Assuming a used car or lease qualifies for the new loan deduction: The temporary personal deduction generally requires a qualifying new vehicle and excludes lease payments.
- Assuming a 2026 EV purchase earns a federal credit: The new, previously owned, and commercial clean-vehicle credits generally are unavailable for vehicles acquired after September 30, 2025, subject to transition rules.
A practical way to choose a method
- Separate business, commuting, and personal miles.
- Confirm that the trips have a qualifying business purpose.
- Check whether the vehicle and its depreciation history permit standard mileage.
- Calculate business miles using the correct rate for each part of 2026.
- Total actual costs, including the business share of interest, depreciation, or lease payments.
- Compare the two eligible results.
- Keep the mileage log, receipts, loan statements, lease documents, and purchase records with your tax files.
For a vehicle bought late in the year, a vehicle used by multiple businesses, or a vehicle with business use near the 50% threshold, professional tax advice can prevent an expensive method or depreciation error.
FAQ
Can I write off my entire car if I use it for business?
Usually no. You can generally deduct only the qualifying business-use portion, using either the standard-mileage method or actual expenses. Depreciation, Section 179, bonus depreciation, and passenger-vehicle limits may further restrict the amount.
Is driving from home to work deductible?
Usually no. Home-to-regular-workplace travel is commuting and is generally personal. Travel between workplaces, to customers, suppliers, or qualifying temporary work locations may be deductible when properly documented.
Can I claim IRS mileage and gasoline for the same vehicle?
Generally no for the same year. The standard-mileage rate already accounts for gasoline, repairs, insurance, depreciation, and other ordinary vehicle costs. Eligible parking and tolls can generally be added separately.
Can employees deduct unreimbursed mileage on their federal tax return?
Most employees cannot. The federal miscellaneous itemized deduction for unreimbursed employee travel expenses remains suspended for most employees, although limited statutory exceptions apply. An accountable-plan reimbursement from the employer is usually the normal alternative.
The Bottom Line
Keep a contemporaneous mileage log, separate commuting from genuine business travel, and compare standard mileage with actual expenses before filing. Buying an expensive SUV or financing a new car does not automatically make the vehicle fully deductible. The correct result depends on business-use percentage, vehicle classification, depreciation limits, loan or lease terms, and the tax year.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




