Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallUsually, a car-insurance refund is a return of premium you paid for coverage that will not be provided after the policy’s cancellation or change date. It is often called an unearned-premium refund. But canceling a policy does not automatically produce a full refund—or even a check sent directly to you.
The amount and timing depend on your state, the policy’s cancellation terms, whether the insurer uses pro-rata or short-rate accounting, fees and taxes, outstanding balances, and whether your premium was financed. Get the cancellation or change confirmed in writing, keep replacement coverage active so you do not create a gap, and request a written refund calculation.
As an Amazon Associate I earn from qualifying purchases.
What a car-insurance refund actually is
When you pay an insurance premium in advance, the insurer gradually “earns” that premium as it provides coverage. If the policy ends before its scheduled expiration date, the portion allocated to the unused period may be unearned and potentially refundable.
A simple way to think about the accounting is:
Premium paid in advance − premium earned for coverage already provided = possible unearned premium
#1 Best Overall

- 👁️Quick Accessible: Inside the car insurance and registration card holder, the clear inner material makes you easy to find documents when you open it up, you can see exactly what they are and quickly show them when asked, even no need to take the stuff out.
- 💼Document Well Organized: The car document holder keeps your car documents organized and keep them tidy and secured, which make it easy to quickly identify and reach paper or cards in the folder. The glove box organizer for car has 6 compartments to keep all your car essential auto car essentials organized.
- 🧲Hidden Magnetic Closure: The glove box document holder are built with hidden magnetic closure, which will keep your car paperwork organizer neat and tidy and ensure the certifications stay closely and and completely protective within the registration pouch.
- 💖Premium Material: The car manual holder is made from high-quality ECO-friendly PU leather material. The car insurance holders with the best sewing and crafted is durable, wear-resistant, and has a luxurious look. This material of the registration holders is durable, wear resistant and waterproof. The insurance card holder for car has a clear window so you can easily see all the documents when you open it up.
- 🌷Compact Size: With the perfect size dimensions of 5.0in x 9.4in x 0.4in, this vehicle license and registration holder for car will fit into glove compartments, sun visors, door holders, consoles, etc. The glove box organizer is precisely designed to fit all of your car documents.
The amount you ultimately receive may be lower after an allowed cancellation charge, minimum-earned-premium provision, nonrefundable fee, tax or assessment adjustment, installment balance, prior credit, or premium-finance balance.
This is different from a claim payment, a lower renewal rate, a discount, a deductible reimbursement, or a refund for a vehicle service contract or extended warranty.
When you might be owed money
| Situation | What may happen |
|---|---|
| You cancel the policy midterm | The unused portion may be refunded or credited, subject to the policy, state law, and cancellation method. |
| The insurer cancels the policy | Unearned premium may still be refundable, although an unpaid balance or other adjustment can reduce the amount. |
| You remove a vehicle, driver, or optional coverage | The change may create a credit or refund for the coverage no longer provided. |
| You replace your insurer | The old insurer may refund unused premium after the cancellation is processed. Replacement coverage should begin before the old policy ends. |
| The policy is flat-canceled or rescinded | This can involve different rules from an ordinary midterm cancellation. In some circumstances, all premium may be returned, but these are specialized and state-specific concepts. |
| Your premium was financed | The refund may go to the premium-finance company or reduce the financed balance instead of being paid directly to you. |
Canceling because you sold the car or found a cheaper policy
Selling a vehicle, moving to a state where the insurer does not operate, finding a lower rate, or replacing the policy are common reasons to cancel. Washington’s insurance regulator specifically advises consumers to check possible cancellation fees and arrange replacement coverage before canceling.
Do not let the old policy end first. Arrange replacement coverage effective before cancellation. If you need a new policy, you can compare car insurance quotes or contact an independent, state-licensed agent; confirm that the insurer is authorized in your state and compare limits, deductibles, exclusions, and effective dates—not just price. A comparison service does not guarantee savings, and a lapse can lead to higher rates.
Removing a vehicle or coverage
You do not always need to cancel an entire policy to create a refund. Removing a vehicle, driver, endorsement, or optional coverage can change the premium. The result may be a check, a credit against the next bill, or no immediate payment if the adjustment is absorbed by an existing balance.
Ask whether the change was processed as an endorsement and request the effective date. Texas regulatory materials describe unearned premium as including amounts that result from cancellation or termination of a policy or an endorsement. That does not make Texas’s treatment a nationwide rule; your policy and state requirements control.
If the insurer cancels you
An insurer’s cancellation does not necessarily mean the unused premium disappears. Depending on the reason for cancellation, state rules, the effective date, and what you owe, the insurer may have to return unearned premium or apply it to another amount due.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Read the cancellation notice carefully. It should identify the effective date and, depending on the jurisdiction and reason, may explain the notice period or reason for termination. Arrange replacement coverage before that effective date. Do not assume that a pending refund means you remain insured after the stated cancellation date.
How the refund is calculated
Earned versus unearned premium
The insurer first determines how much premium was earned for the time or coverage already provided. The remaining prepaid amount is the starting point for a possible refund.
Rank #2
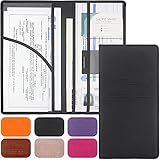
- 💼 CAR ORGANIZER PRACTICALITY: Car registration and insurance holder has multi-function clear compartments which can organize various items very well. The car document holder large pocket for insurance documents and 2 pockets for vehicle registration, 3 small pockets for driver's license, ID cards, AAA cards, business cards, receipt, key contact information cards, etc. It can fully meet your needs
- 👁EASY TO ACCESS AND READ: Car registration and insurance holder keeps your documents organized and keep them tidy and secured, which is stress-free to identify the documents in the folder and quickly reach the document when asked
- 🧲MAGNETIC CLOSURE DESIGN: The car insurance card holder is built with inner magnetic closure, which will keep your vehicle paperwork organizer closed to secure your vehicle documents from humidity and wear and tear. The car insurance holder is your first choice for protecting important car documents and certificates
- ✨PREMIUM MATERIAL: Car registration and insurance holder are made of high-quality PU leather and vinyl PVC. The beautiful cover of 3d embossing provides a comfortable soft touch feeling and professional look. This material is durable, Tolerant, and looks very naturally beautiful
- 💖SECURED & ASSURED: If you have any product problem when you use our car registration and insurance holder. Please feel free to contact us by email, we will do our best to offer a satisfactory solution for you within 24 hours
For example, California’s official auto-insurance glossary illustrates a pro-rata calculation using an annual premium of $1,000 and cancellation after 40 days. The earned portion is approximately $110, leaving approximately $890 as the unearned portion before applicable adjustments. That example explains the method; it is not a promise that every policy will produce an $890 refund.
A different policy might use a $1,200 annual premium and a 90-day cancellation. A simple pro-rata estimate would be:
- Daily premium: $1,200 ÷ 365 = about $3.29
- Earned premium for 90 days: about $295.89
- Unearned premium before adjustments: about $904.11
The actual result could differ because of policy terms, billing practices, state rules, fees, taxes, endorsements, or a short-rate calculation.
Pro-rata cancellation
Under a pro-rata approach, the insurer charges for the exact period of coverage provided and returns the remaining unearned amount, subject to applicable adjustments. There is generally no separate short-rate penalty in a pure pro-rata calculation.
Short-rate cancellation
Under a short-rate approach, the insurer may retain more than the exact daily cost to account for administrative expense when the policyholder—not the insurer—chooses to cancel. The refund can therefore be smaller than a simple day-by-day estimate.
California’s official residential-insurance guidance describes policyholder-initiated cancellation as generally being calculated on a short-rate basis, while noting that some companies use pro-rata accounting. That guidance illustrates why a generic online calculator cannot determine every auto-insurance refund. The applicable auto policy, endorsements, state law, broker or agency agreement, taxes, installment charges, and premium-finance contract are more authoritative.
Other deductions and adjustments
Before accepting the insurer’s figure, ask whether it includes:
- A short-rate cancellation charge
- A minimum-earned-premium provision
- Nonrefundable policy, broker, agency, or administrative fees
- Taxes, assessments, or other government charges
- Installment or payment-plan charges
- Premium already owed from an earlier bill
- Prior credits or returned payments
- A claim or endorsement that changed the earned premium
- An amount owed to a premium-finance company
A claim does not automatically eliminate a refund. Whether money remains refundable depends on the policy language, the amount of coverage already provided, the claim or loss circumstances, and the applicable state rules.
Why the refund may not come directly to you
Premium-financed policies
If a finance company paid the insurer on your behalf, the insurer may send the unearned premium to that finance company. The money may be applied to your financed balance rather than sent to your bank account.
Rank #3

- PREMIUM: A fashionably slim, all-in-one design, the CoBak leather car document holder offers solid protection along with space for your essential documents. The case holder is handcrafted from premium-quality PU leather and present of luxurious lining.
- QUCIK ACCESS: This car document holder is a great way to keep all of your important documents together. Clear inner PVC pouches makes it easy to identify the papers or cards you need, with only one glance you will know exactly where the documents are when asked.
- MAGNETIC CLOSURE: Strong built-in magnets ensure the files and documents will be well protected and closed like a breeze.
- 6 COMPARMENTS: Comes with 3 large pockets for insurance documents, vehicle registrations cards and other valueable information. And 3 small pocket for driver's license, ID cards, business cards, key contact information cards.
- COMPACT SIZE: 9.5" x 5.1"(24cm x 13cm), slim profile and lightweight design, perfect size for any glove box or console compartment, ideal choice to protect your important documents. Also a great gift for yourself, lovers, friends and family.
Read the premium-finance contract separately from the insurance policy. California consumer guidance warns that a policyholder may still owe the finance company the full premium required under the finance contract even after canceling the insurance midterm. In other words, canceling coverage and satisfying the financing agreement are related but separate issues.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →If the insurer says a refund was issued, ask for:
- The date and amount of the refund
- The recipient or payment destination
- The finance account to which it was applied
- The remaining balance after the application
- Any separate cancellation or finance charge
Credits on the insurance account
An insurer may apply a refund as a credit against another premium due on the same policy or account. That can be reasonable under the policy or state rule, but ask for a ledger showing the credit and the remaining balance.
Federal Regulation Z contains rules concerning credit balances in certain credit transactions, including some balances created by insurance-premium rebates. Those provisions apply in a narrower credit-transaction context; they are not a universal deadline or automatic-refund rule for every auto policy.
How long does a car-insurance refund take?
There is no single nationwide refund deadline that applies to every U.S. auto-insurance policy. The controlling deadline may come from state insurance law, the policy, the billing agreement, or the premium-finance contract. The relevant date may also depend on when the insurer receives your cancellation request and the effective cancellation date.
Texas example: Texas insurance regulatory materials describe a requirement to refund unearned premium within 15 business days from the later of the insurer’s receipt of the cancellation notice or the cancellation or termination date. The materials also permit a credit against other premium due on the same policy unless the policyholder requests otherwise. This is a Texas example, not a national rule.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Washington consumer guidance emphasizes reviewing the insurer’s cancellation policy and possible fees rather than relying on a universal timing rule. If your policy or state department gives a specific deadline, use that deadline and document the date the insurer received your request.
What to do: a step-by-step refund process
- Arrange replacement coverage first. If you are switching insurers, make the new policy effective before the old one terminates. Verify the effective date, vehicles, drivers, liability limits, deductibles, and required coverage.
- Send the cancellation or change request in a trackable form. Use the method your insurer requires. State the policy number, requested change, and requested effective date. Keep the message and proof of delivery.
- Obtain written confirmation. Ask the insurer to confirm whether the entire policy was canceled or only a vehicle, driver, or coverage was removed, and ask for the exact effective date.
- Request the accounting. Ask for total premium paid, earned premium, unearned premium, cancellation method, each fee or adjustment, outstanding balance, and the net amount payable.
- Check where the money is going. If your premium was financed, ask whether the refund is being sent to the finance company or applied to the financed balance.
- Compare the accounting with the policy. Review the declarations page, cancellation provision, endorsements, billing statements, and any premium-finance agreement. Look specifically for pro-rata or short-rate language, minimum-earned-premium terms, and nonrefundable charges.
- Track the expected deadline. Record the date the cancellation request was received, the effective date, the date the refund was approved, and the promised payment date.
- Follow up in writing. If the payment is late or the calculation is unclear, contact billing or policy services and ask for a written explanation rather than relying only on a telephone promise.
- Escalate to the regulator if necessary. If the insurer does not resolve the issue, contact your state insurance department. The National Association of Insurance Commissioners provides a directory for locating the appropriate state department and submitting a complaint.
Keep a refund file
Save the cancellation request, confirmation, cancellation notice, declarations page, policy wording, endorsements, payment receipts, billing ledger, finance agreement, refund check or electronic-payment record, and every email or letter. A simple folder or spreadsheet can help you organize insurance documents and record dates, amounts, and responses. A document-organizing service can help with recordkeeping, but it cannot determine whether a refund is legally owed.
Questions to ask the insurer
Use this list when requesting a refund calculation:
- What is the exact cancellation or coverage-change effective date?
- Was the calculation pro-rata or short-rate?
- How much premium was earned, and how was that figure calculated?
- How much unearned premium remains?
- Was a cancellation fee, minimum-earned premium, or nonrefundable fee deducted?
- Were taxes, assessments, installment charges, or agency fees included?
- Was any amount applied to an unpaid bill or another policy?
- Was the premium financed, and if so, who will receive the refund?
- Is the amount a refund, an account credit, or a reduction of a finance balance?
- When will the payment be issued, and by what method?
Flat cancellation and rescission are not ordinary refunds
Two terms can create confusion:
- Flat cancellation: The policy is canceled as of its effective date, so there is no premium charge for coverage under that policy.
- Rescission: The policy is treated as canceled back to its effective date. California’s consumer glossary describes rescission as producing a return of all premium charged.
These terms can have specific legal and contractual meanings. California materials illustrate the terminology, but a rescission or flat-cancellation remedy should not be assumed in another state or treated as the normal result of a midterm cancellation.
Recommended Free Tools
Rank #4

- 【HIGH QUALITY】: made of premium PU leather and durable vinyl PVC, strong and firm enough for your long-term use.
- 【SAFE PROTECTION】: this registration and insurance card holder keeps your document free from tearing, bending or being ruined by moisture.
- 【TIME SAVER】: clear inner pouches design helps you identify the correct document quickly with one glance.
- 【WIDE RANGE OF USES】: can store your bills, insurance cards, vehicle registration and other essential paperwork.
- 【SPECIAL GIFT】: beautiful sleek and trim design. This car document holder is a good gift for yourself, your lover, friends and family.
What if the insurer refuses or delays the refund?
First, ask the insurer to identify the precise policy provision or state rule supporting its decision. Request the billing ledger and a written explanation of every deduction. Confirm that the insurer used the correct effective date and processed the request as a cancellation rather than leaving the policy active or treating it as a missed payment.
If the response is incomplete, escalate to a supervisor or the insurer’s formal complaint channel. Send a concise written timeline with copies—not originals—of your supporting documents.
Next, file a complaint with the insurance department in the state that regulates the policy. A regulator can review whether the insurer followed applicable insurance rules, although it generally cannot rewrite the policy or guarantee a particular refund amount.
For a large, unusually complex, or persistently disputed matter, you may also consider an insurance consumer advocate or qualified local insurance attorney after the insurer and regulator steps. Check the person’s jurisdiction, credentials, fees, and scope of service, and do not assume that any advocate can guarantee recovery.
Do not confuse auto-insurance refunds with service-contract refunds
A vehicle service contract, mechanical breakdown plan, or extended warranty is not the same product as ordinary auto liability or physical-damage insurance. Washington, for example, has separate rules for auto service-contract cancellations, which can involve full or prorated refunds and cancellation fees. Those rules do not establish the refund rights for a standard car-insurance policy.
Why your state matters
Auto insurance is primarily regulated at the state level in the United States. State rules can address cancellation notices, refund timing, permissible fees, premium accounting, and complaint procedures. The National Association of Insurance Commissioners notes that each state has its own insurance rules, and most states require at least basic auto coverage.
California, Texas, and Washington are useful illustrations—not universal standards:
- California: Official materials distinguish pro-rata, short-rate, flat cancellation, and rescission concepts. California’s residential-insurance guidance is useful for explaining cancellation accounting but should not be treated as an automatic rule for every auto policy nationwide.
- Texas: Regulatory materials provide a specific 15-business-day example for returning unearned premium, measured from the later of the insurer’s receipt of the cancellation notice or the cancellation or termination date.
- Washington: Consumer guidance stresses checking cancellation fees and avoiding a coverage lapse, which can contribute to higher rates.
For a definitive answer, use your policy and the insurance department in the state governing the policy—not a national calculator or an estimate based on another state.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteRefund request template
You can adapt this message to your insurer:
Subject: Written cancellation confirmation and unearned-premium accounting for policy [number]
Best Value
 ESSENTIAL Car Auto Insurance Registration BLACK Document Wallet Holders 2 Pack - [BUNDLE, 2pcs] - Automobile, Motorcycle, Truck, Trailer Vinyl ID Holder & Visor Storage - Strong Closure On Each -
- ESSENTIAL Car Auto Insurance Registration BLACK Document Wallet Holders 2 Pieces
Please confirm that my policy or coverage change was processed effective [date]. Please provide a written accounting showing the total premium paid, earned premium, unearned premium, calculation method, cancellation or other fees, taxes and assessments, outstanding balance, and net refund or account credit.
If the premium was financed, please identify whether the refund will be sent to the finance company or applied to the financed balance. Please also state the expected issue date and payment method. Thank you.
Official guidance to consult
For the most authoritative answer, compare the insurer’s policy and billing documents with guidance from your state insurance department. National Association of Insurance Commissioners consumer materials explain the general concept that either the policyholder or insurer may cancel and that part of the premium may be refundable, while state regulators provide the rules that determine how and when the refund is handled. Federal Regulation Z may be relevant only when the insurance premium is connected to a covered credit transaction.
Free tools Windows power users keep installed
One-click scans. No signup required.
Frequently Asked Questions
Do I get a refund if I cancel my car insurance?
Often, you may receive or be credited with the unearned portion of premium paid for coverage after the effective cancellation date. The amount depends on your state, policy terms, pro-rata or short-rate accounting, fees, balances, and whether the premium was financed. It is not automatically a full refund.
How is a car-insurance refund calculated?
The insurer generally subtracts the premium earned for coverage already provided from the premium paid in advance. A pro-rata calculation charges for the exact coverage period, while a short-rate calculation may let the insurer retain an additional cancellation amount. Fees, taxes, minimum-earned-premium terms, balances, and financing can change the net result.
How long does an auto-insurance refund take?
There is no single nationwide deadline. State law, the policy, and the billing or finance agreement may control. As one state-specific example, Texas regulatory materials describe 15 business days from the later of the insurer’s receipt of the cancellation notice or the cancellation or termination date.
Can I get a refund if my insurer cancels me?
You may still be owed unearned premium for coverage that was not provided, but an unpaid balance or other permitted adjustment can reduce or eliminate the payment. Read the cancellation notice, confirm the effective date, and request a written accounting.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWhat happens if I financed my insurance premium?
The insurer may send the refund to the premium-finance company or apply it to the financed balance instead of paying you directly. Your finance contract may also require you to pay a balance after midterm cancellation, so review both agreements.
Does filing a claim prevent an insurance refund?
Not automatically. The answer depends on the policy, the coverage already provided, the claim or loss, remaining premium, and applicable state rules. Ask for the insurer’s written calculation rather than assuming either a full refund or no refund.
What should I do if the insurer refuses or delays my refund?
Request the policy provision, billing ledger, calculation method, effective date, and written reason for the decision. Escalate to the insurer’s billing or complaint department, then contact your state insurance department if the issue remains unresolved. Keep all cancellation, payment, policy, and correspondence records.
Can canceling my car insurance create a coverage gap?
Yes. If you are replacing the policy, make the new policy effective before the old one ends and verify the dates in writing. A lapse can expose you to uninsured losses and may contribute to higher rates.
Recommended Free Tools
The Bottom Line
Bottom line: A car-insurance refund usually means the return of unearned premium, not an automatic full repayment. Confirm the effective date, ask whether the calculation is pro-rata or short-rate, review every deduction and outstanding balance, check whether a finance company receives the money, and escalate in writing to your insurer and state insurance department if the accounting or timing is not explained.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




